▸ Record Q1 net revenue of $1.396B (+13.1%) and net income of $160M (+64.9%) — yet long-term guidance withheld
▸ Total debt nearly doubled from $6.3B to $12.2B; covenant cap raised 4.25x → 4.75x as synergy recognition is frozen
▸ Four fault lines tested at once: the scale-equals-survival thesis, FCC's waiver game, the broken merger-arb model, industry-wide reshuffling
▸ A philosophical reversal from 2018's blocked Sinclair–Tribune deal — whichever way this lands, the playbook for U.S. broadcast M&A will be rewritten
Even with a federal injunction effectively prohibiting the integration of the two companies, Nexstar Media Group — the largest local-television owner in the United States — posted record first-quarter results after closing its $6.2 billion acquisition of TEGNA.
In a release issued May 7, Nexstar reported Q1 net revenue of $1.396 billion, up 13.1% year-on-year; net income of $160 million, up 64.9%; and adjusted EBITDA of $470 million for a 33.7% margin. Distribution and advertising revenues rose 9.8% and 19.1% respectively. Combined with $56 million in dividends paid in Q1 and $182 million of debt repaid through the end of April, the headline numbers read less like "post-deal integration synergies" than a demonstration of operating momentum under conditions where integration itself is blocked.
 Jung Han
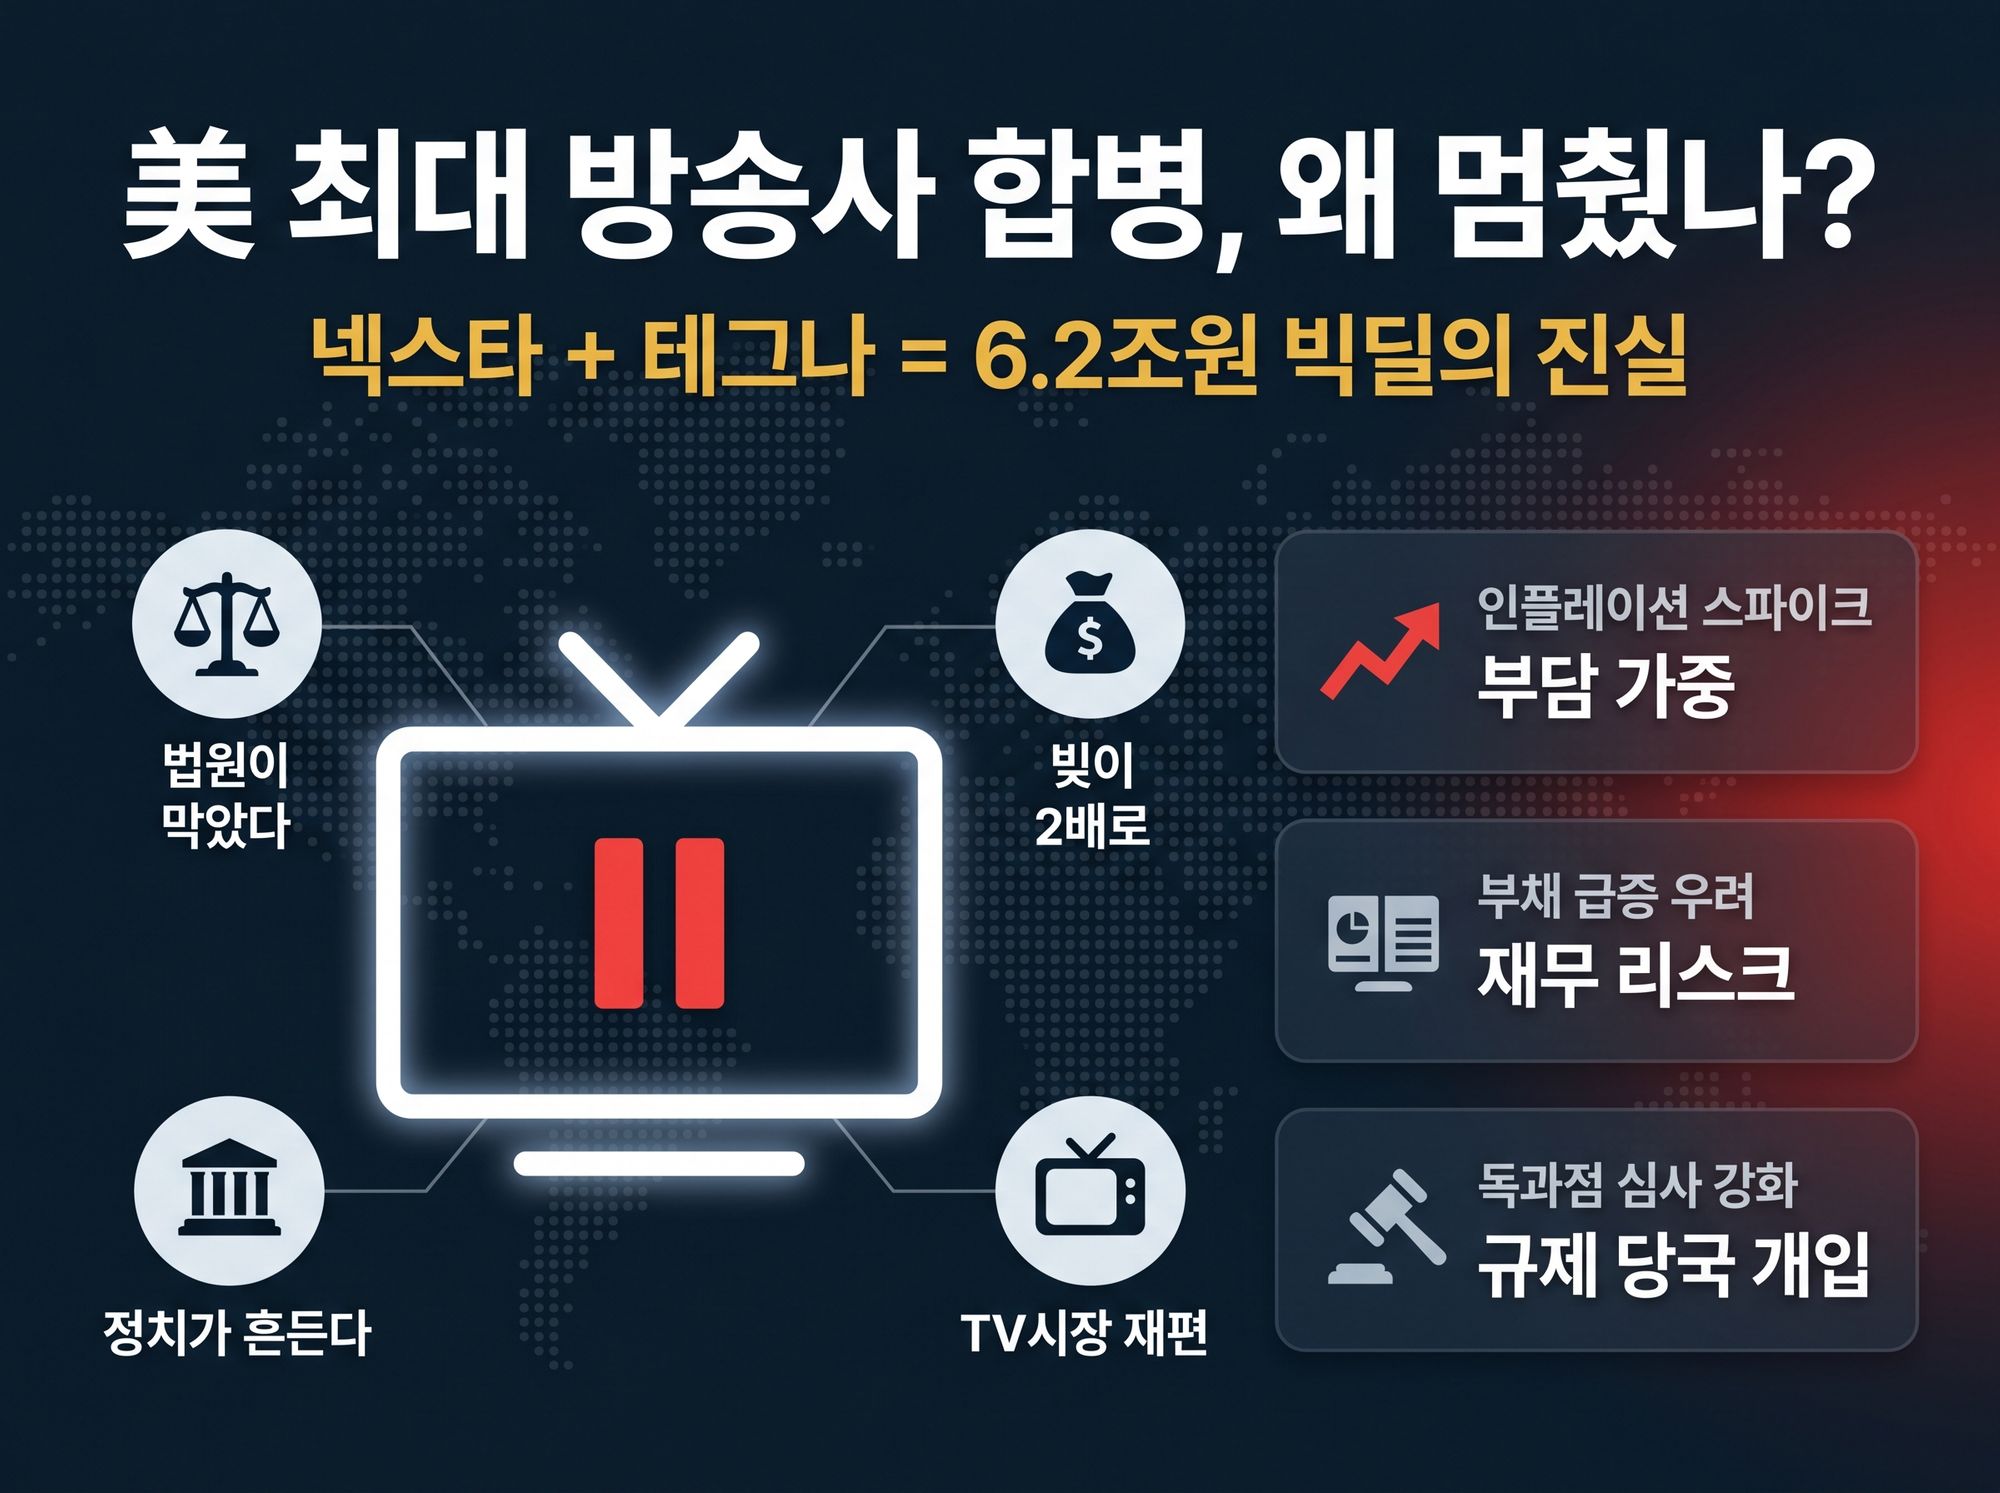
And yet management took the unusual step of refusing to provide long-term guidance on the earnings call. Nexstar's pro-forma debt has nearly doubled — from roughly $6.3 billion before the deal to about $12.2 billion at quarter-end — forcing the company to negotiate a temporary lift of its first-lien net leverage covenant from 4.25x to 4.75x. That combination tells the real story: the strong print is not so much confirmation of a stable growth trajectory as it is the paradox of a scale-and-consolidation strategy whose clock has been stopped by judicial risk.